At the France Trading Conference 2026, held by the FIX Trading Community in Paris on 17 September, one conclusion connected conversations that ranged from equity liquidity and European regulation to tokenisation and prediction markets: market innovation is accelerating, but its value depends on the quality of the infrastructure, data and safeguards that support it.
European markets are not facing a simple shortage of liquidity. They are dealing with a redistribution of liquidity across more venues, protocols and counterparties. At the same time, Europe is trying to direct more savings towards productive investment, modernise its market infrastructure and attract a new generation of investors. These objectives are related. Together, they define the next phase of European capital-market development
The short answer
What is changing in European capital markets? Five shifts stood out from the day:
- Liquidity is moving beyond continuous lit order books into bilateral channels, dark pools, systematic internalisers and periodic auctions.
- Best execution increasingly depends on measuring the complete outcome of an order, not simply accessing more venues or paying a lower commission.
- Europe needs deeper market integration if it is to turn its substantial savings base into investment, innovation and growth.
- Tokenisation will only scale when tokenised and traditional instruments are interoperable, fungible and supported by clear investor rights.
- Digital engagement can widen participation, but prediction markets and gamified trading sharpen the distinction between access and speculation.
Liquidity is changing location, not disappearing
The equity-market discussions challenged the idea that European liquidity is simply deteriorating. Early regulatory analysis suggests that aggregate liquidity remains relatively stable. What has changed is where and how trading takes place.
Continuous lit order books now represent a smaller share of execution, while frequent batch auctions, dark pools, systematic internalisers and bilateral liquidity have become more prominent. Closing auctions remain major liquidity events. For market participants, this creates more choice and more opportunities to reduce market impact. It also makes the execution decision more complex.
The key market-structure question is whether robust price formation can be preserved if a growing share of execution relies on reference prices formed elsewhere. The panel discussions did not point to an immediate failure of European price formation. They did, however, underline the need to monitor spreads, accessible liquidity, execution quality and venue behaviour, particularly during volatile periods.
Alternative liquidity must deliver a measurable benefit
Bilateral liquidity can add genuine value when an institutional investor needs to execute a large order that cannot be absorbed efficiently by a central order book. Direct interaction with a market maker or electronic liquidity provider may improve execution certainty and reduce market impact. Buy-side-to-buy-side crossing can also uncover natural liquidity that would otherwise remain unavailable.
The case is less obvious for small orders. If a systematic internaliser or liquidity provider offers the same price as the lit market without meaningful price improvement, the investor may be providing valuable, lower-risk institutional flow without receiving a sufficient benefit in return. The principle expressed during the panel was straightforward: better-quality flow should be matched by better economics, stronger execution certainty or another demonstrable improvement.
Best execution is becoming an evidence problem
No venue or protocol is universally superior. A routing decision should reflect the objective and characteristics of the order: urgency, size, information-leakage risk, expected fill rate, potential price improvement, post-trade reversion and the quantity still to execute.
A periodic auction may be useful for a VWAP strategy seeking to limit information leakage. Bilateral liquidity may be more appropriate for a larger liquidity-seeking order. A passive lit order can earn part of the spread and may outperform an apparently attractive midpoint execution once the full economics are considered.
This is why transaction cost analysis must measure the whole result. Explicit commission is only one component. Fill rate, spread captured or paid, market impact, adverse selection, price reversion and implementation shortfall can matter far more. One of the most striking observations from the market-structure panel was that the difference between the best- and worst-performing broker Smart Order Routers could exceed one basis point even for relatively small orders. Routing quality is therefore a material execution cost, not a technical detail.
Regulation must protect price formation without freezing innovation
European regulation continues to influence which execution mechanisms gain or lose market share. Changes to volume caps, transparency requirements and the treatment of systematic internalisers can alter behaviour quickly.
The discussions supported proportionate intervention. Periodic auctions and systematic internalisers can meet legitimate execution needs. Regulation should respond to clearly identified problems and assess the effect of any restriction on European competitiveness. This matters because investors view Europe as an interconnected investment region even as the European Union and the United Kingdom pursue different regulatory paths.
The European consolidated tape could improve the common view of prices and volumes, lower the cost of post-trade analysis and give the buy side and its brokers a shared evidence base. Yet data quality and granularity remain decisive. Without sufficient information on systematic-internaliser trades, it is difficult to assess objectively their execution quality or contribution to price formation.
Europe has capital but still needs to connect it to opportunity
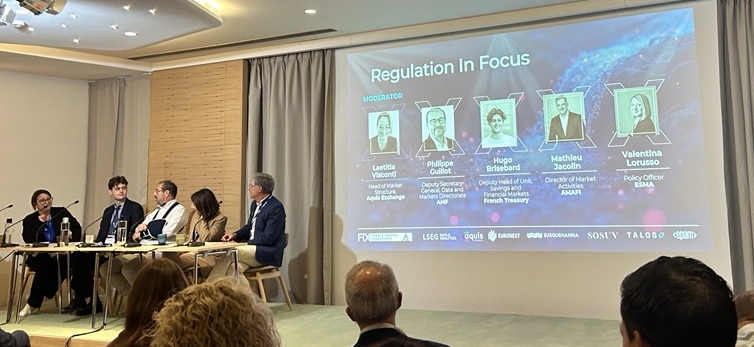
The debate on French and European capital markets highlighted a familiar paradox. Europe has substantial household savings, major asset managers, strong banks, established market infrastructure and deep technical talent. Yet too little of that capital reaches European companies and innovation through public markets.
France illustrates both the strength and the opportunity. Paris combines global financial institutions, institutional investors, listed companies, fintech expertise and an expanding international financial community. Its position becomes more valuable when connected to a broader European investor base rather than developed in isolation.
The Savings and Investments Union and the proposed Market Integration and Supervision package aim to make cross-border activity easier, reduce fragmentation and build the scale that national markets cannot create independently. Success will depend not only on regulation, but also on market infrastructure capable of supporting efficient access, transparent data and cross-border execution.
Tokenisation needs fungibility more than novelty
Tokenisation could bring issuance, trading and settlement closer together, reduce operational friction and support more continuous access to some instruments. But the panel discussions were clear that technology alone does not create a functioning market.
A tokenised security must confer rights equivalent to those of its traditional counterpart. Where both forms coexist, investors need to move between them without creating duplicate instruments, losing claims on dividends or weakening ownership rights. Interoperability, fungibility and legal certainty are therefore prerequisites for scale. Tokenisation is likely to progress through controlled use cases rather than an immediate market-wide transition.
Gamification can broaden access or distort incentives
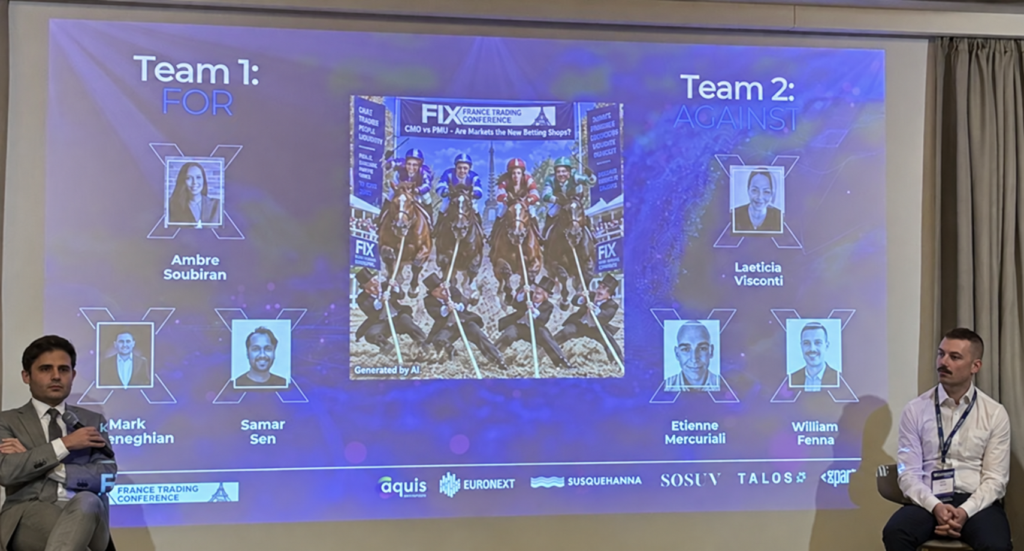
The final debate extended beyond prediction markets to digital assets, fractional trading, mobile platforms and the emergence of multi-asset “everything brokerages”. Supporters argued that engaging, digital-first experiences can lower barriers and introduce younger investors to financial markets. This could help Europe reconnect household savings with capital-market participation.
The risk arises when design is used to maximise trading frequency rather than improve decisions. Leaderboards, rewards, streaks, leverage and very short-duration contracts can encourage speculation, particularly where platform revenues increase with activity. Prediction markets add questions about market manipulation, privileged information and the possibility that market probabilities become self-reinforcing signals.
A useful regulatory distinction is not between modern and traditional interfaces, but between accessible design and manipulative incentives. Product governance, market-abuse controls and clear information about loss probability and product risk will determine whether digital engagement becomes a route to sustainable participation or merely a new form of betting.
What the day means for trading infrastructure
Across these discussions, the same requirement kept returning: firms need infrastructure that can adapt as liquidity, regulation and investor behaviour change. More venues do not automatically produce better execution. More data does not automatically produce better decisions. The advantage comes from combining access with configurable routing, transparent analytics, operational controls and the ability to prove the outcome.
That makes interoperability and standards strategically important. In a market spanning lit and dark venues, bilateral relationships, traditional and tokenised assets, brokers and investors need consistent workflows and reliable data if innovation is to translate into resilient execution.
Conclusion
FIX Trading Paris 2026 presented a market at the edge of change, but not one moving in a single direction. Europe is simultaneously opening new liquidity channels, reinforcing oversight, exploring digital forms of ownership and seeking wider retail participation.
The central challenge is to make these developments work together. The market participants that succeed will be those able to access innovation without losing transparency, measure execution without oversimplifying it and build greater participation without compromising trust.
Editorial sources
This blog draws on the conference notes supplied by Horizon and the following public sources:
The discussions suggested that overall liquidity remains relatively stable, but its distribution is changing. More execution is taking place through periodic auctions, dark pools, systematic internalisers and bilateral channels rather than continuous lit order books alone. Because no venue is best for every order. A SOR must consider order size, urgency, expected fill rate, price improvement, information leakage, venue cost and post-trade performance, then adapt the routing decision accordingly. No. They can provide midpoint liquidity and reduce some forms of latency arbitrage, but passive lit execution can capture part of the spread. The complete outcome should be assessed through transaction cost analysis. Fungibility, interoperability, equivalent investor rights, legal certainty and reliable links between trading and settlement infrastructure are essential. Technology alone is insufficient. No. Accessible interfaces can lower barriers and improve engagement. The risk comes from incentives and design patterns that encourage excessive activity, leverage or speculation rather than informed decision-making.Frequently Asked Questions